Then vs Now: How People Actually Bought Their First Home
Jovanni Chan
September 9, 2026
Buying your first home has never been a small decision. For generations, it has meant saving money, taking on a large loan and committing to a place that may shape years of your life.
What has changed is the path people take to get there.
A first-time buyer several decades ago dealt with higher mortgage rates at certain points, fewer financing options and a much more manual buying process. Today’s buyer can browse thousands of properties from a phone and compare mortgages online, but may also face high home prices, expensive rents and fierce competition for properties.
The old story that previous generations simply worked hard, saved a little and easily bought a house is too simple. So is the idea that buying a home was always just as difficult as it is today.
The challenges changed.
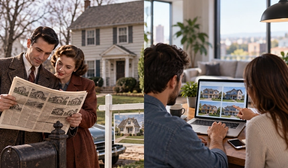
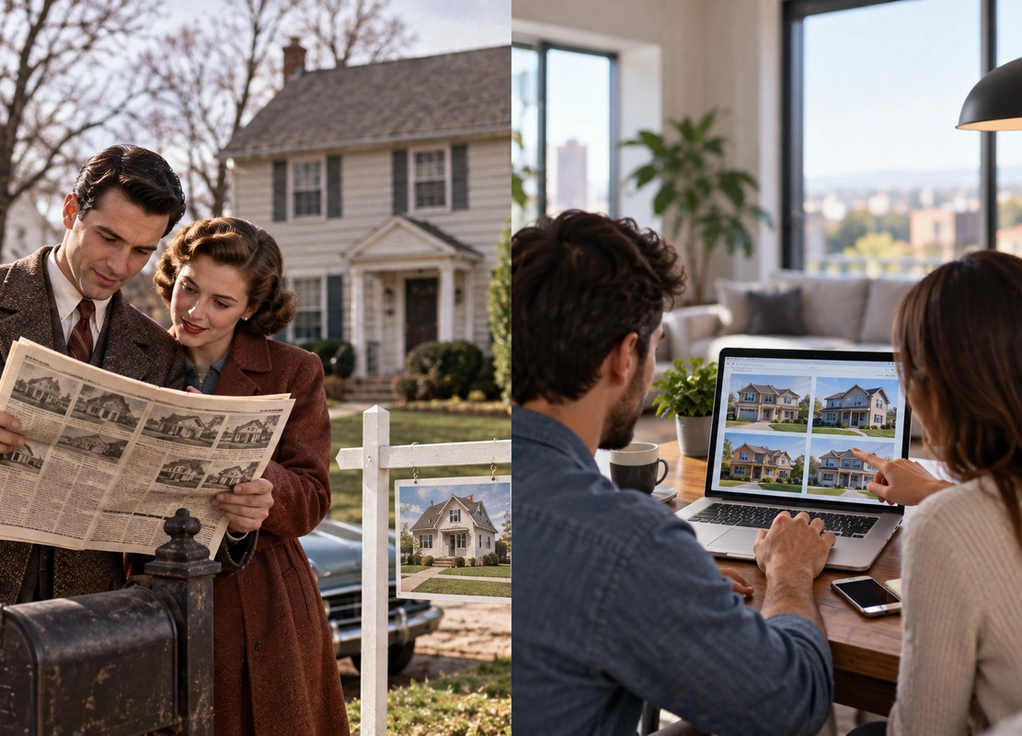
Finding a home once started with a newspaper
A modern buyer can look at homes without leaving bed.
Property websites provide photographs, floor plans, price histories, neighborhood information and sometimes virtual tours. Alerts can notify buyers within minutes when a new property appears.
Earlier buyers had far less information.
Newspaper classified advertisements were an important place to find homes for sale. Yard signs mattered. Real estate agents maintained listings and often controlled access to much of the information buyers needed.
If you wanted to see a house, you generally had to arrange an actual viewing.
There was no casually examining 40 kitchens on your phone during lunch.
This made real estate more local. Buyers depended heavily on agents, relatives and their own knowledge of neighborhoods.
Today, buyers have dramatically more information, although having more information does not necessarily make choosing easier.
Saving for a deposit looked different
Previous generations are often remembered as buying homes shortly after starting adult life.
Some did.
But there was never one universal experience. Family income, location, race, lending access and economic conditions all influenced who could buy and when.
What was different in many markets was the relationship between income and home prices.
In places where houses cost a smaller multiple of annual household income, accumulating a deposit could be more achievable even when salaries were much lower in dollar terms.
Today’s buyers can face a frustrating cycle.
High rent makes it difficult to save. While they are saving, home prices may rise. The amount required for a deposit therefore moves further away even as their savings grow.
This is one reason first-time buyers increasingly rely on family assistance in some expensive housing markets.
The deposit is not always the only problem. It is getting the deposit while continuing to pay for somewhere else to live.
Mortgage rates tell only half the story
Older homeowners sometimes point out that mortgage rates were dramatically higher in previous decades.
They are correct.
American mortgage rates reached extraordinary levels around the early 1980s. Buyers could face interest rates that would seem almost unimaginable to someone who purchased a home during the ultra-low-rate period of the 2010s or early 2020s.
That made monthly borrowing expensive.
But comparing interest rates alone creates a distorted picture.
The price of the home matters too.
A high interest rate on a relatively inexpensive property creates a different financial challenge from a lower rate on a much more expensive property.
Buyers also had opportunities to refinance when rates later declined.
The useful question is not whether one generation had higher mortgage rates.
It is how much of a household’s income was required to buy and finance a typical home at that particular moment.
The bank relationship was much more personal
Applying for a mortgage once involved considerably more paper.
Buyers visited banks, completed physical forms and provided stacks of financial documents. Loan officers played a direct role in guiding applicants through the process.
Today, much of that experience can happen digitally.
Buyers can compare lenders online, upload documents, receive preapproval electronically and track an application without repeatedly visiting a branch.
Technology made the process faster and gave consumers easier access to comparisons.
But mortgage approval remains fundamentally interested in the same questions.
How much do you earn? How much debt do you have? How reliable is your financial history? Can you afford the payments?
The forms changed.
The bank’s concerns did not.
The starter home was actually a category
For many previous buyers, the first house was not expected to be the final house.
A young couple might buy a modest property, build equity and move to a larger home after their income increased or their family grew.
This idea created the “property ladder.”
The first home was simply the first rung.
In some modern housing markets, that first rung has become much harder to reach.
Smaller homes may be in limited supply, particularly in areas where land and construction costs encourage developers to build more expensive properties.
A first-time buyer may therefore find themselves competing not only with other young households but also with investors, downsizers and existing homeowners.
The starter home still exists.
In some places, it simply does not feel priced like one anymore.
Buyers knew much less before making an offer
Modern house hunting produces an extraordinary amount of research.
Before viewing a property, a buyer might already know when it last sold, what nearby houses cost, how long it has been listed and whether the asking price has changed.
They can examine satellite images, commute times and neighborhood reviews.
Earlier buyers operated with less visibility.
They could ask an agent about comparable properties and investigate the neighborhood, but obtaining information required much more effort.
That sometimes meant making decisions with greater uncertainty.
Modern buyers have the opposite problem.
They can research so much that every house develops 40 potential reasons not to buy it.
More information reduces some risks while creating entirely new forms of anxiety.
The definition of a first home changed
Expectations have changed too.
Previous generations often bought houses that would now be considered unfinished or outdated.
A first home might have a small kitchen, one bathroom and no air conditioning. Renovations happened gradually as money became available.
Modern property media has changed what buyers see as normal.
People spend years looking at professionally photographed homes, renovation programs and perfectly styled interiors online. Features that were once luxuries can begin to feel like basic expectations.
That does not mean younger buyers are simply too demanding to afford houses, as the argument is sometimes presented.
Housing affordability is a much larger economic issue.
But visual culture has undoubtedly changed what the dream home looks like.
Buying a home was never equally easy for everyone
Any comparison between generations needs to acknowledge one uncomfortable reality.
Access to homeownership has never been equal.
In the United States, discriminatory lending practices, racial covenants, redlining and other policies historically prevented many families from accessing the same housing and mortgage opportunities available to others.
Those differences had consequences lasting far beyond one generation.
A home is not simply somewhere to live. It can become an asset passed between generations or provide parents with resources that later help their children buy homes.
When one generation was excluded from those opportunities, the financial effects could continue decades later.
There was never a single historical experience of “buying your first house.”
Today’s process is easier while affordability can be harder
This is the strange contradiction of modern home buying.
Almost every administrative part of the process became easier.
Finding listings is easier. Comparing mortgages is easier. Researching neighborhoods is easier. Communicating with agents is easier. Signing documents can even happen electronically.
Actually affording the house can be the difficult part.
Previous generations dealt with their own serious obstacles, including periods of extremely high interest rates and far less consumer-friendly technology.
But many modern first-time buyers face high purchase prices while simultaneously dealing with expensive rent and other living costs.
The tools for buying a house have never been better.
That does not mean the house itself has become easier to buy.
The dream stayed remarkably similar
Despite everything that changed, the reasons people want their first home remain familiar.
They want stability. They want more control over where they live. They want somewhere they can decorate, renovate and make their own. Many hope the property will become a source of long-term financial security.
The process around that dream has transformed.
Newspaper listings became property apps. Bank appointments became online applications. Paper maps became neighborhood searches. The starter home became harder to find in many markets.
But receiving the keys to a place that is finally yours still represents something very similar to what it did generations ago.
The route changed.
The milestone did not.