Why “Saving Money” Meant Something Different in Every Era
Emory Frye
September 9, 2026
“Save your money” sounds like advice that should mean exactly the same thing in every generation.
It doesn’t.
What people considered saving depended heavily on the world around them. Bank accounts changed. Inflation changed. Credit became easier to access. Retirement plans shifted responsibility from employers to individuals. Investing moved from something that often required a broker to something anyone could do from a phone.
Even the reason for saving changed. One generation saved to survive uncertain times. Another saved for a house. Another was told to build a retirement portfolio while simultaneously paying student loans and expensive rent.
The principle stayed remarkably consistent. The purpose, tools and expectations surrounding it did not.
The 1930s made saving about security
The Great Depression shaped financial attitudes for generations.
People who experienced bank failures, unemployment and severe economic uncertainty often developed an intense preference for financial security. Saving was not necessarily about maximizing returns. It was about making sure something was available when things went wrong.
Cash mattered.
So did avoiding waste. Food was reused rather than casually thrown away. Clothing was repaired. Household objects were kept for years because replacing something unnecessarily meant spending money that might be needed later.
These habits often survived long after the Depression ended.
Children and grandchildren sometimes wondered why older relatives kept drawers full of string, jars or reusable containers. For people shaped by genuine scarcity, throwing away something useful could feel almost irresponsible.
Saving money was partly financial behavior and partly a way of thinking.
The postwar years made saving about building a life
After World War II, saving increasingly became connected to major milestones.
Families saved for homes, cars, appliances and education. Rising prosperity allowed more households to think beyond immediate survival and toward long-term goals.
Banks played a central role.
A savings account represented safety and progress. Children were encouraged to put coins into piggy banks before eventually opening accounts of their own.
There was also a stronger cultural distinction between saving for something and borrowing to get it immediately.
Consumer credit certainly existed and expanded during this period, but many households still approached large purchases with the expectation that money would first be accumulated.
You wanted something.
You saved.
Then you bought it.
That sequence would gradually become much less rigid.
The 1970s showed what inflation could do to savings
The inflation of the 1970s introduced a painful lesson.
Money sitting safely in cash could still lose value.
If prices rise quickly, the same amount of money buys less over time. Someone can watch the number in a savings account remain unchanged while its purchasing power quietly declines.
Interest rates eventually rose dramatically as well, creating unusual conditions for savers and borrowers.
For savers, higher rates could mean more attractive returns on certain bank deposits. For borrowers, especially people seeking mortgages, high interest rates could make loans extremely expensive.
Saving therefore became more obviously connected to interest rates and inflation.
Keeping money safe was not the only concern.
People also had to consider whether their savings were actually keeping up with rising prices.
The 1980s and 1990s connected saving with investing
As retirement systems changed, the meaning of saving expanded.
Putting money into a bank account was no longer enough to describe someone’s long-term financial strategy.
Employer-sponsored retirement accounts such as 401(k)s became increasingly important in the United States. Workers were encouraged to contribute part of each paycheck and invest that money for retirement.
This introduced millions of ordinary households to a different concept.
You did not simply save money.
You invested it.
The distinction mattered. Savings accounts were useful for money that needed to remain accessible and relatively stable. Retirement money had decades to potentially grow and could therefore be invested in assets that fluctuated in value.
For many households, wealth building became increasingly tied to financial markets.
Credit changed the reason people needed savings
As credit cards became widespread, consumers gained an alternative to waiting.
You no longer necessarily needed to save the full price of something before buying it.
That was enormously convenient.
It was also dangerous when borrowing became a substitute for having emergency savings.
A broken appliance or unexpected car repair could be placed on a credit card instead of paid from money already set aside. The immediate problem disappeared, but it could return as debt carrying substantial interest.
This made the emergency fund increasingly important.
Modern financial advice often separates emergency savings from other goals for exactly this reason.
The money is not supposed to earn spectacular returns.
It exists to stop an ordinary financial surprise from becoming expensive debt.
The 2000s made saving automatic
Technology gradually removed much of the effort involved in saving.
Employers could automatically send retirement contributions from each paycheck. Banks allowed customers to schedule recurring transfers. Online accounts made balances available without visiting a branch.
This encouraged a powerful idea: save before you have the opportunity to spend.
Instead of reaching the end of the month and saving whatever remained, money could automatically move into savings immediately after income arrived.
For people who struggled to save consistently, automation changed the process from repeated decision-making into a background habit.
The technology was new.
The underlying advice was extremely old.
Pay yourself first.
Millennials had to save for several futures at once
For many Millennials, saving became complicated by competing financial goals.
Build an emergency fund. Pay student loans. Save for a house deposit. Contribute to retirement. Prepare for children. Invest for the future.
All of these can be sensible goals.
Doing them simultaneously is much harder.
High housing costs in many cities made the problem particularly visible. Someone could be saving responsibly every month while watching the amount required for a home deposit increase at the same time.
This changed the emotional experience of saving.
Earlier generations often associated saving with eventually reaching a specific purchase.
For younger adults, saving can sometimes feel like continuously trying to prevent major financial goals from moving further away.
Apps turned saving into something almost invisible
By the 2010s and 2020s, saving could happen without touching physical money at all.
Banking apps could automatically move funds between accounts. Investment platforms could schedule recurring purchases. Some services could round transactions and save or invest the difference.
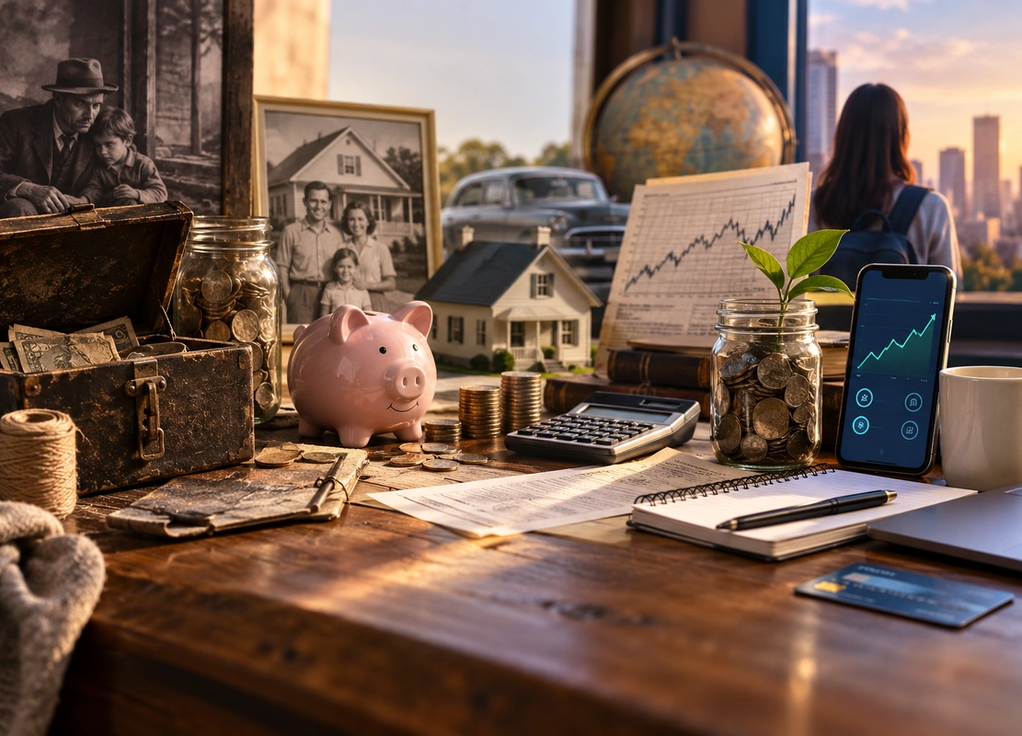
The physical piggy bank had effectively become software.
This made saving easier in some ways, but digital money also made spending easier.
A person paying with cash can physically see money leaving their wallet. Contactless payments reduce that experience to a tap. Online shopping can complete a purchase in seconds.
Modern consumers therefore live with two opposing technologies.
It has never been easier to automate saving.
It has also never been easier to spend money without thinking very much about it.
Saving is no longer automatically enough
Perhaps the biggest modern change is the recognition that saving and investing serve different purposes.
Money needed for an emergency or a near-term purchase generally needs stability and accessibility.
Money intended for goals decades away has a different problem.
Inflation.
If long-term money grows more slowly than prices, its real purchasing power can decline.
That is why modern conversations about building wealth tend to include investing alongside saving.
The old advice to “put money away” remains useful.
The important question is what you are putting it away for.
Every generation was saving against a different fear
The Depression generation feared having nothing when disaster arrived.
Postwar families saved to buy homes and build stable lives.
Workers later in the century increasingly saved for retirement as responsibility shifted toward individual accounts.
Younger generations are often trying to prepare for several expensive milestones while protecting themselves against economic uncertainty.
The financial products changed, but the emotional reason for saving remained remarkably familiar.
People save because the future is uncertain.
A savings account, retirement portfolio or envelope of emergency cash is ultimately an attempt to give your future self more options.
That is the part of “saving money” that never really changed.